Who Should Use biBERK? Best Use Cases by Business Type
Introduction
Choosing a business insurer starts with one practical question: does this carrier fit my kind of business? A coverage list alone does not answer it. A bakery, a consulting firm, and a delivery service need very different protection, and a carrier that suits one may frustrate another.
This guide answers who should use biBERK by working through specific business types. It explains which policies each type usually needs, where biBERK‘s direct, online model helps, and where owners should compare other options. The examples are illustrative, not guarantees of eligibility. Final availability, pricing, and terms depend on your state, operations, and underwriting.
Table of contents
Quick Summary: Who Is biBERK Best For?
biBERK works best for small businesses with standard, well-understood risks that want to buy core commercial policies online. It fits less well for businesses with specialized exposures or owners who want an advisor to manage every decision.
- Strong fit: Offices and professional services, restaurants and food service, retail, cleaning services, light contractors, fitness and beauty businesses, and small delivery or service operations with light vehicles.
- Possible fit, with more checking: Healthcare practices, transportation, property management, and higher-hazard trades.
- Weaker fit: Highly specialized industries, personal insurance needs, and owners who want a broker to compare many carriers.
- Smart next step: Request a quote, then compare it with one other source using the same limits.
| Business type | Policies commonly considered | Fit with biBERK’s model |
|---|---|---|
| Consultants, accountants, IT firms | Professional liability, general liability, BOP | Strong |
| Restaurants and bakeries | BOP, workers’ compensation, general liability | Strong |
| Retail shops | BOP, general liability, workers’ compensation | Strong |
| Cleaning and janitorial services | General liability, workers’ compensation | Strong |
| Light contractors and trades | General liability, workers’ compensation, commercial auto | Check classes and state |
| Delivery and field services | Commercial auto, umbrella | Check vehicle and driver rules |
| Healthcare practices | Professional liability, BOP | Check eligibility |
How Does biBERK – Small Business Insurance Relate to This Question?
biBERK – Small Business Insurance is a direct-to-business offering. According to biBERK’s commercial insurance page, the company insures small businesses directly, without a middleman or broker, and advertises savings of up to 20% compared with other insurers. Treat that figure as a company claim. Your own quote is the only reliable measure for your business.
The model shapes who benefits. Because biBERK sells directly, owners who know what they need can move quickly. Because it concentrates on core small business policies, owners who need unusual coverage may hit a ceiling. Therefore, “who should use biBERK” mostly depends on two things: how standard your risks are, and how much guidance you want during the purchase.
What Policies Does biBERK Sell?
biBERK’s product overview lists workers’ compensation, professional liability (errors and omissions), general liability, business owners policy (BOP), commercial auto, and umbrella insurance. Some third-party sources also list cyber insurance, so confirm current availability for your state. This article refers to these policy types throughout as it matches them to business types.
Who Should Use biBERK? A Fit Test Before the Details
Before reading the business-type sections, test your own situation against a few criteria. A business that answers “yes” to most of the following tends to suit a direct carrier.
What Characteristics Make a Business a Good Match?
- Your operations are common and easy to describe in a short online form.
- You need core policies, not specialized or niche endorsements.
- You feel comfortable reading policy terms yourself.
- You value speed and want to buy online.
- You can compare a quote against one other source.
In contrast, businesses with several locations, complex contracts, or unusual hazards often benefit from broker guidance. That does not rule biBERK out. It simply means the biBERK quote should be one data point, not the final decision.
Does Business Size Matter?
biBERK focuses on small businesses. In a state-level general liability analysis, MoneyGeek described biBERK as most often the cheapest for solo operators in Connecticut, within certain industries. That finding is specific to one state and one dataset, so do not generalize it. Still, it suggests that very small operations may find the direct model competitive. Larger employers with big payrolls should compare more carefully, because workers’ compensation costs scale with payroll and classification.
Which Professional Services Firms Should Use biBERK?
Office-based and professional businesses often carry lower physical risk but face liability from advice and services. For them, the policy mix differs from a storefront.
Why Do Consultants, Accountants, and IT Firms Fit Well?
A third-party agent guide describes biBERK‘s professional liability coverage as aimed at professional services firms such as consultants, IT professionals, accountants, architects, engineers, and real estate agents. Professional liability, also called errors and omissions, addresses claims that your advice or work product caused a client financial harm. General liability usually does not respond to those claims.
For example, a freelance IT consultant who misconfigures a client’s system could face a negligence claim. General liability would likely not cover it, while professional liability might. A consultant with a client office visit risk might also want general liability. biBERK’s multi-policy menu lets such a firm assemble both from one carrier.
Which Policies Should a Professional Services Firm Prioritize?
- Professional liability (E&O): The core protection for advice-based work.
- General liability or a BOP: Useful if clients visit or you own office equipment.
- Workers’ compensation: Required in many states once you hire employees.
- Umbrella: Worth considering if client contracts demand higher limits.
Check contract language first. Clients often specify minimum limits, and the cheapest policy fails if it does not meet them.
Which Restaurants and Food Businesses Should Use biBERK?
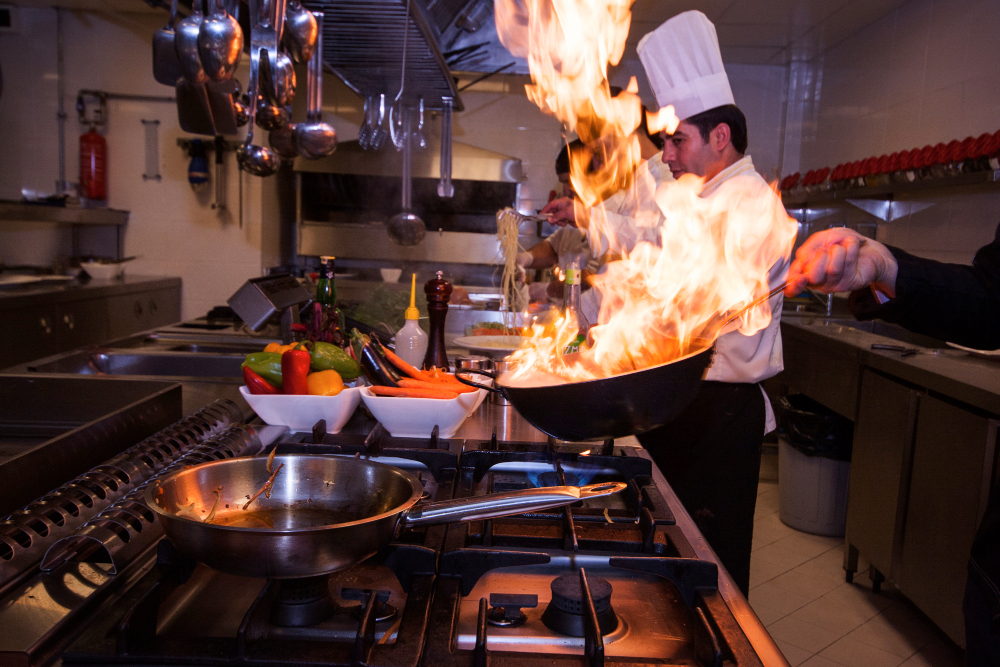
Food businesses combine customer-facing liability, property exposure, and employee injury risk. As a result, they often need several policies.
Why Might a BOP Suit a Bakery or Restaurant?
A business owners policy bundles property and liability coverage. biBERK lists bakeries among the industries it insures, and restaurants appear on its industry list. For a small bakery with ovens, display cases, and walk-in customers, a BOP can cover equipment and customer-injury claims in one policy.
The key detail is replacement cost. Commercial ovens and refrigeration cost more than owners often expect. Before accepting a BOP, compare its property limit with a realistic equipment inventory, and ask how it handles spoilage or equipment-breakdown claims, since those depend on endorsements and policy terms.
What About Workers’ Compensation in a Kitchen?
Kitchens involve burns, cuts, and slips. Workers’ compensation covers medical costs and part of lost wages for employee injuries on the job. A third-party agent guide lists restaurants among the classes biBERK writes workers’ compensation for. Because rules and pricing vary by state, confirm your state’s requirements and your payroll classification before buying.
Which Retail Businesses Should Use biBERK?
Retail businesses sit near the center of biBERK‘s target market. A storefront has inventory, customers, and employees, which maps neatly onto a BOP plus workers’ compensation.
How Do Boutiques and Local Shops Use These Policies?
A boutique with five employees and a leased space typically needs liability protection for customer injuries, property protection for stock and fixtures, and workers’ compensation. biBERK’s general liability page lists retail stores and services among the industries that typically need liability coverage, and it notes situations such as selling a physical product to customers or using third-party locations.
Consider a pop-up seller who rents a market stall. A landlord or event organizer may require proof of general liability before the event. An online purchase and a certificate of insurance can help here, but confirm how quickly biBERK issues certificates and whether an organizer needs additional insured status.
Where Might Retailers Need More Than the Basics?
Stores that sell high-risk products, import goods, or ship internationally may face product liability issues beyond a standard policy. In those cases, read the exclusions carefully and ask whether additional coverage is available. Otherwise, you could discover a gap only after a claim.
Which Cleaning and Janitorial Services Should Use biBERK?
Cleaning services rely on small teams, mobile work, and client trust. Insurance requirements often appear directly in commercial cleaning contracts.
Why Do Cleaning Businesses Appear as a Strong Match?
biBERK lists cleaning and janitorial companies among the businesses it serves. In addition, MoneyGeek’s state analyses for North Carolina and Connecticut described biBERK as generally the most affordable for cleaning services and fitness facilities in general liability pricing. Those results apply to specific states, dates, and sample profiles. Therefore, use them as a prompt to request a quote, not as proof of price.
Which Coverage Combination Makes Sense?
A typical commercial cleaner needs general liability for damage claims, such as a spill that ruins a client’s flooring, and workers’ compensation for employee injuries. Some clients also ask for proof of coverage for employee dishonesty or theft, which is a separate coverage question. Ask biBERK whether such coverage is available rather than assuming a standard policy includes it.
Which Contractors and Trades Should Use biBERK?
Contractors face the widest range of hazards, so the answer here depends heavily on the trade.
Are Light Contractors a Good Fit?
Also, biBERK‘s target classes include light contractors, and it lists trades such as electrical, plumbing, HVAC, painting, and general contracting among those it writes well. biBERK’s own pages also list contractors and construction companies among the industries it insures. Trades with lower physical hazard tend to be the easiest to place.
However, the same agent guide frames pricing as most competitive for low-to-moderate hazard classes. Roofing, tree work, and heavy construction usually carry higher hazards, so confirm whether those classes are eligible in your state.
Why Should Contractors Check Their Contract Requirements?
biBERK’s general liability page notes that state and federal law can require general liability for independent contractors in certain industries such as construction. Contractors should check licensing rules and project contracts. Many general contractors require subcontractors to carry specific limits and to name them as additional insureds. Confirm that biBERK can meet those terms before you commit.
What About Commercial Auto for Trades?
Personal auto policies often exclude business use. For example, a plumber who drives a work truck needs commercial auto coverage. The agent guide describes biBERK’s commercial auto program as best suited to contractors, service businesses, and delivery operations with light-to-medium vehicles. Heavier trucks or long-haul operations call for closer comparison.
Which Fitness and Beauty Businesses Should Use biBERK?
Personal service businesses blend customer contact with relatively modest property needs.
Why Might Gyms, Studios, and Salons Fit?
Third-party sources list beauty and barber shops and fitness studios among the businesses biBERK writes. A yoga studio, for example, faces customer injury claims, while a salon faces product-reaction and slip-and-fall claims. General liability handles many of these third-party risks, and a BOP can add property protection for equipment.
What Should Owners Verify Before Buying?
Two details matter. First, confirm whether professional-style claims, such as an injury from a treatment, fall under general liability or require a separate professional liability policy. Second, check how the policy treats independent instructors or booth renters. Many owners assume contractors are covered under the studio’s policy, but coverage depends on the policy wording.
Which Healthcare and Medical Practices Should Use biBERK?

Healthcare appears in biBERK‘s list of industries served, including medical practices and healthcare facilities. However, healthcare risks vary widely, so this category deserves extra caution.
Can a Small Medical Office Use biBERK?
A small medical or dental office may need professional liability, general liability, or a BOP, and workers’ compensation. Professional liability for clinicians often involves specialized limits and requirements from hospitals or insurers. Consequently, request a biBERK quote but also compare it against a carrier that specializes in medical malpractice if your practice delivers clinical care.
What Questions Should You Ask?
- Does the professional liability policy meet our licensing or credentialing requirements?
- Are claims-made terms and tail coverage explained clearly?
- Are all practitioners and locations included?
These questions apply to any professional liability policy, and written answers reduce surprises later.
Which Delivery, Transportation, and Property Businesses Should Check biBERK?
Some industries appear on biBERK’s lists but need more verification before you assume a fit.
How Should Delivery and Transportation Businesses Evaluate It?
biBERK’s commercial insurance pages list transportation and trucking companies among industries served. Meanwhile, the agent guide frames the commercial auto program around light-to-medium vehicles. A courier with two vans differs from a trucking company with a fleet. If you operate heavier vehicles, confirm eligibility, driver requirements, and limits before relying on a quote.
Do Landlords and Property Managers Have Options?
biBERK lists landlords and property management companies among its industries. A small landlord may use a BOP or general liability, while a property manager might need professional liability for management errors. Check whether the policy covers the building itself or only your business operations, because owners sometimes confuse the two.
Who Should Not Rely Only on biBERK?
A fair assessment includes the cases where another route may work better.
Which Situations Call for a Broker or Specialist?
- Specialized industries, such as certain technology, manufacturing, or high-hazard trades.
- Businesses with multiple locations or complicated contracts.
- Owners who want one advisor to coordinate property, liability, and personal insurance.
- Businesses that need coverage lines biBERK does not sell.
biBERK also does not appoint individual retail agents. According to its partner page, it works through select wholesaler partners. If your agent cannot access biBERK, you will likely buy directly.
Does biBERK Replace Personal Insurance?
No. A 2026 third-party review states that biBERK does not quote personal auto or home policies. Sole proprietors should confirm how business activity at home or in a personal vehicle is treated, and keep personal and commercial policies separate.
How Can You Match biBERK Coverage to Your Business Type?
A structured approach prevents both underinsurance and overpaying. Work through the steps below.
What Is a Practical Decision Process?
- List your exposures. Think about customers, employees, property, vehicles, advice, and data.
- Check requirements. Review state law, leases, client contracts, and lender terms.
- Map exposures to policies. Use the table below as a starting point.
- Request a biBERK quote. Enter accurate details about operations and payroll.
- Compare one alternative. Match limits, deductibles, and key endorsements.
- Read the policy forms. Focus on exclusions and conditions.
| Exposure | Policy that usually addresses it |
|---|---|
| Customer injury or property damage | General liability |
| Equipment, inventory, and building contents | BOP or property coverage |
| Employee injury | Workers’ compensation |
| Client claims about advice or services | Professional liability |
| Business vehicles | Commercial auto |
| Claims above liability limits | Umbrella |
How Do You Avoid Common Mistakes?
Owners often choose the lowest premium without checking limits. Others describe operations loosely to speed up the form. Both errors can cause trouble later. Describe your work accurately, record payroll honestly, and keep documents where your team can find them. These habits protect you with any insurer.
Conclusion: So, Who Should Use biBERK?
So, who should use biBERK? In short, small businesses with standard risks that want to buy core commercial policies online. Professional services firms, restaurants and bakeries, retail shops, cleaning services, light contractors, and fitness or beauty businesses all align with the industries biBERK lists. Healthcare, transportation, and higher-hazard trades deserve extra verification.
biBERK – Small Business Insurance offers a reasonable starting point for these owners, particularly when speed matters. Even so, confirm every claim about savings, eligibility, and availability with your own quote. Match coverage to your contracts, compare at least one alternative, and read the exclusions before you buy.
Frequently Asked Questions
biBERK describes its focus as small businesses. Very small operations may find the direct model convenient, but larger employers should compare more carefully because workers’ compensation and liability costs rise with payroll and exposure.
Possibly. Freelancers often need professional liability and general liability, and some clients require proof of coverage. Confirm your classification and state eligibility through a quote.
It can be for lower-hazard trades. A third-party agent guide lists electrical, plumbing, HVAC, painting, and general contracting among classes biBERK writes well. Higher-hazard trades need eligibility and pricing confirmation.
biBERK lists commercial auto among its products. The agent guide suggests it suits light-to-medium vehicles, so confirm limits and driver requirements for your fleet.
Yes. Compare a biBERK quote with at least one other source using identical limits and deductibles. Price alone shouldn’t decide your choice.
What Are the Benefits of Cooperating With Solution for Guru?
Solution4Guru helps businesses evaluate products and services through practical, research-based content. Working with the team can help you:
- Turn complex product information into clear, decision-ready guidance.
- Compare options using consistent criteria, not marketing claims.
- Reach owners, managers, and decision-makers who are actively researching solutions.
- Publish content that follows clear editorial standards for accuracy and readability.
Recommended
- Verizon Connect for Landscaping Companies
- Verizon Connect Mobile App Overview
- How Does Motive Support Business Growth?
- Why Do Construction Companies Choose Motive?
- Driver Safety Monitoring with Azuga: How Can Fleets Reduce Risk and Build Safer Habits?
- Benefits of Using Samsara for Fleet Management
- How Verizon Connect Helps Reduce Insurance Premiums
- How Motive Helps Reduce Insurance Costs
- How Verizon Connect Improves Fleet Productivity
- How Motive Detects Distracted Driving
- Managing Mixed Fleets with Verizon Connect
- How Verizon Connect Improves Driver Accountability
- How Motive Helps Schedule Preventive Maintenance
- How Samsara Improves Fleet Productivity
- How Fleet Managers Use Motive for Compliance Reporting
- How Motive Improves Dispatcher Efficiency
- How Motive Helps Reduce Fleet Operating Costs
- Azuga Review: Features, Pros, Cons, and Best Use Cases
- What Is Azuga Fleet Management Software? A Complete Guide
- Top Reasons Businesses Choose Motive Fleet Management
- Samsara Review: Features, Pros, Cons, and Best Use Cases